Prefer to listen? The report is also an episode of the Maui Real Estate Advisor podcast.
You may have seen the headline that Maui condo sales jumped more than 50% in September compared with a year ago. It's ture, and it's also the kind of number that can fool you, because September 2025 was one of the weakest condo months in two years. So this month we are doing something different. We pulled three full years of data, October 2023 through September 2026, and lined up each year against the one before it. The longer view tells a clearer story than any single month can. The typical Maui condo sale is down about 30% from two years ago, and for roughly the past year prices appear to be leveling off. Sales are up about 20% year over year. And mortgage rates have now climbed seven weeks in a row to 7.40%. For condo buyers, that combination may make this one of the better windows in several years. For condo owners who keep telling us they'd like to sell but don't need to, it carries a very different message. Here is what the data shows, what it means, and where we hedge.
October 2026 Key Takeaways
The three-year view: Condo closings bottomed out and we are climbing again: 879 in the twelve months ending September 2024, 667 the next year, and 798 this past year, up about 20%. Pending sales averaged 102 a month, up 23%.
Condo prices: The median condo sale is down about 29% from two years ago. But the year-over-year decline has narrowed sharply, from about 29% in the third quarter of 2025 to about 3% this past quarter. That looks more like a market finding its floor than one still sliding.
September itself: 72 condo closings, a $660,000 median, and inventory down to 812, a third straight monthly decline.
Supply: At the recent sales pace, about 11 months of condo supply, down from about 16 a year ago. Still a buyer's market, but a less lopsided one.
Mortgage rates: The 30-year fixed hit 7.40% on October 8, up seven straight weeks and more than a full point above a year ago. On a typical financed condo, that costs about as much as a 10% price increase.
For condo sellers: Counting expired and withdrawn listings, about 12 condo listings failed to sell for every 10 that closed this past year, up from about 6 three years ago. Active listings now average 183 days on market. Unless you actually want or need to sell, testing the market is likely to waste your time.
Homes: 52 closings and a $1,150,000 median. Unlike condos, home prices are still softening year over year.
_________________________
A quick word on how we're reading the numbers this month. A single month on Maui is a small sample; a few big closing or a cluster of entry-level sales can swing the median by six figures, as August's $564, 950 reminded us. So this month the foundation is the trailing twelve months and the quarter-by-quarter trend, with September as context rather than the headline. We think that's the better way to read this market, and you'll see more of it from us going forward. Condos first, as always.
Condos
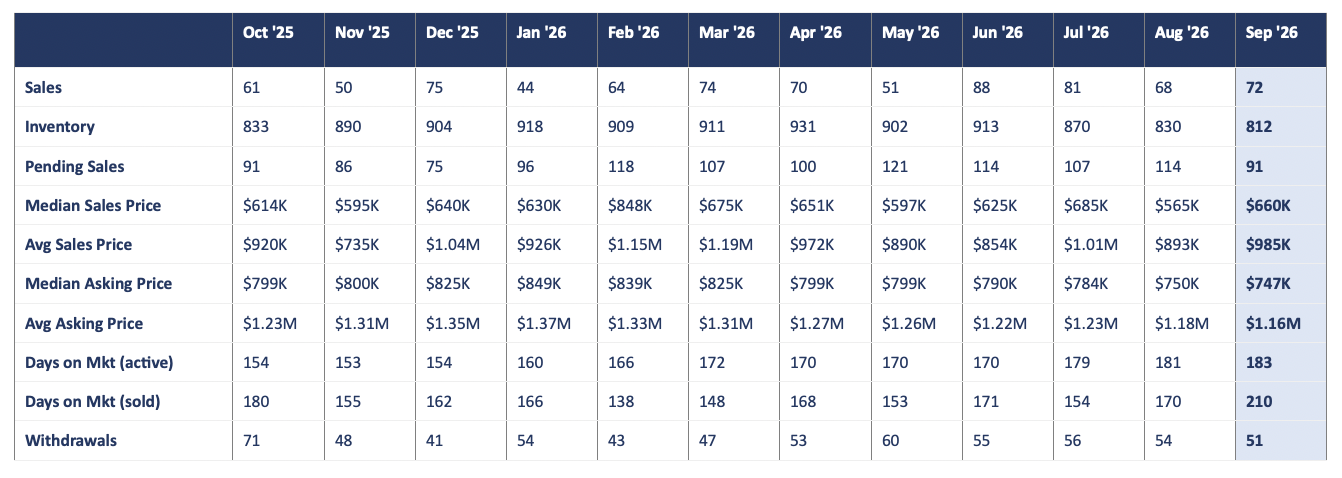
Start with September. 72 condos closed, up from August's 68. The median selling price back to $660,000 from August's $564,950, which settles last month's point that August's dip was about which condos sold, not a price crash. Active inventory fell to 812, down from 830 in August and 913 in June, a third straight monthly decline and 119 fewer listings than April's peak of 931. The softer note: pending sales fell to 91 from 114, so October closings could cool.
That's the month. Now let's look at what three years of data say.
The Bigger Picture
Start with the widest lens: three back-to-back twelve-month periods, each ending in September.
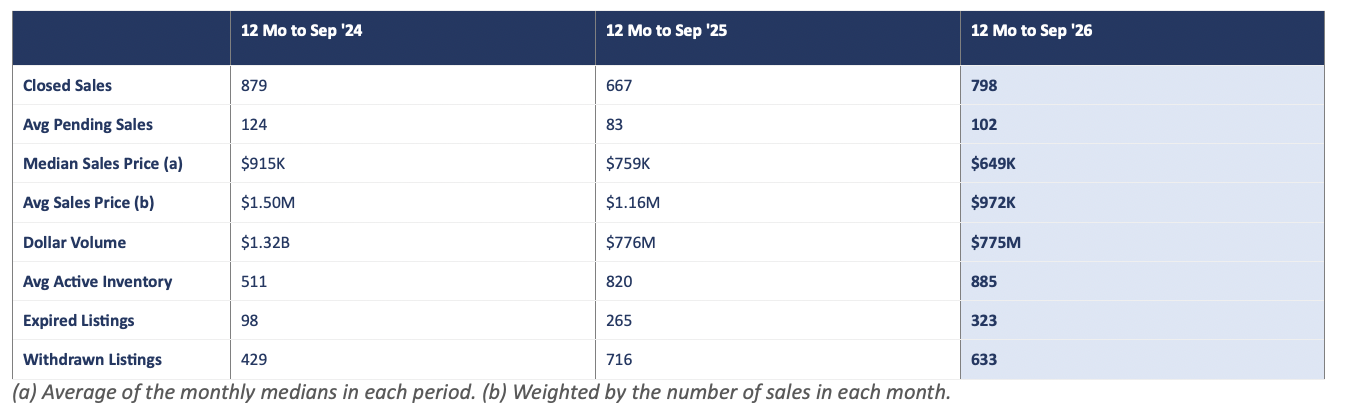
Prices came down hard. Two years ago, over the twelve months ending September 2024, the median condo sale averaged about $915,000. This past year, about $649,000, a drop of roughly 29%. The average sale fell even further, from about $1.50 million to about $972,000, about 35%, partly because fewer luxury condos are trading. Condo dollar volume fell from $1.32 billion to about $775 million. That's the correction, and it was a real one.
Sales hit bottom and turned. Closings fell from 879 to 667, then climbed back to 798, up about 20% this past year. Pending sales followed the same path: 124 a month, then 83, now 102. Note the last two years: total dollar volume was essentially identical, about $775 millin each, but buyers bought about 20% more condos with it.
Now zoom in to the quarter-by-quarter view, which shows when things turned.
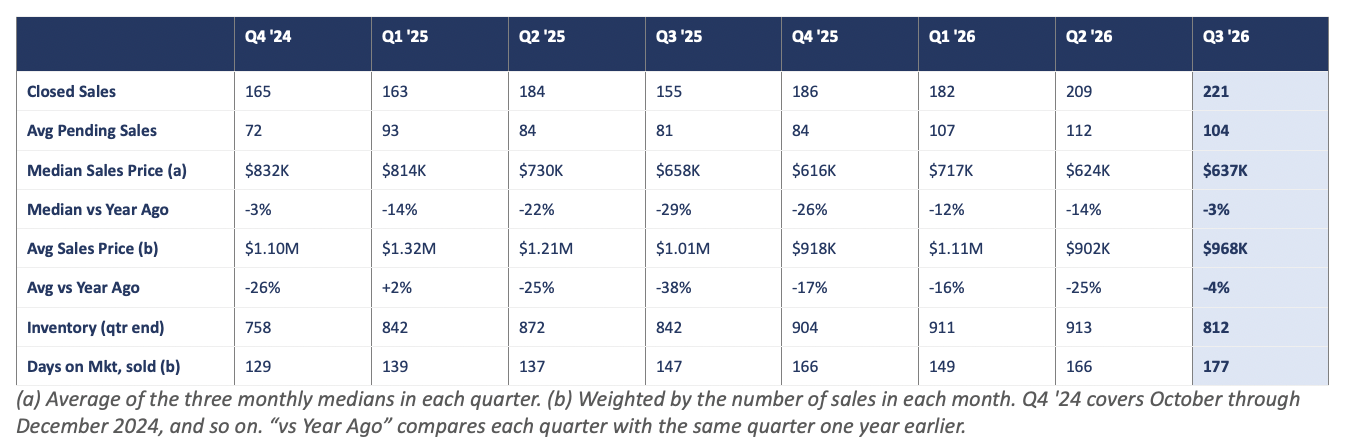
Buyers turned first. Average pending sales bottomed at 72 a month in the fourth quarter of 2024 and have climbed to about 104. Closings followed: the low came in the third quarter of 2025 at 155, and the last two quarters, 209 and 221, are the strongest in this table. The third quarter ran about 43% ahead of the same quarter last year.
Prices turned last, and they're turning now. Look at the "vs Year Ago" rows. The median's year-over-year decline deepened through 2025, from 3% to 14% to 22% to a low point of about 29% in the third quarter of 2025. Since then: 26%, 12%, 14%, and this past quarter, about 3%. The average shows the same arc, bottoming at about 38% down and now about 4%. Meanwhile, three of the last four quarterly median landed between about $616,000 and $637,000, with only the first quarter's spike breaking the pattern.
Buyers first, closings next, prices last. That's the order you would expect when a market is turning the corner, and it's the order this data shows.
For Condo Buyers: Why This May Be the Window
Back in June we wrote that we don't call bottoms, and that anyone who does is selling something. I stand by that, so read this carefully. I am not telling you the bottom is in. Nobody can know that until well after the fact. What I am telling you in that two years of data now look a lot more like a market finding its floor than one still falling, and that the cost of waiting just went up. Here's the case.
Most of the price decline is behind us. The median condo sale is down about 29% from two years ago, and the year-over-year decline has shrunk from about 29% to low single digits. If you've been waiting for Maui condo prices to come down, they did.
Demand is building. Pendings have been rising since last 2024, sales are up about 205 over the year, and the last two quarters of closings are the strongest in our quarterly table. Buyers aren't waiting anymore. They're writing offers.
Supply is tightening, from a high level. At the recent three-month sales pace, today's 812 listings work out to about 11 months of supply. A year ago, the same math said about 16 months of supply. To keep it in perspective, inventory is still far about where it was before the correction: 701 condos for sale in September 2024, and just 215 in September 2023. So buyers still have real choice and real leverage. But the leverage is narrowing.
Sellers have already done a lot of the cutting. The median asking price on active listings fell to $747,000, down from $849,000 in January and from $849,000 a year ago, about 12%. Buyers are the ones collecting on that.
And then there are rates. Freddie Mac's weekly survey put the average 30-year fixed mortgage at 7.40% on October 8, the seventh straight weekly increase, and more than a full point about the 6.30% of a year ago. Take a condo at September's median of $660,000 with 20% down. At 6.30%, principal and interest come to about $3,270 a month. At 7.40%, about $3,660. That is roughly $390 more every month, close to $4,700 a year. To get the same payment at today's rate, that condo would need to cost about $590,000. In other words, the rate move over the past year has already cost a financed buyer about a much as a 10% price cut would save them. And if you're financing a condotel, expect to pay more than that. Most condotels are non-warrantable, which typically means a higher rate and a larger down payment. If your plan has been to wait for another 10% off, rates have already taken it. This is a live demonstration of the 1% equals 10% rule: for every 1 point increase in interest rates, buyers lose about 10% in purchasing power. I can't promise you where rates go next; nobody reliably can. But waiting for both lower prices and lower rates at the same time is a bet on two things going your way at once. A note for our cash buyers, and many of our mainland second-home buyers are exactly that. The rate math doesn't hit your monthly payment, but it still works in your favor. Every tick up in rates thins out the financial buyers competing with you for the same condo, and that's leverage you can use at the negotiationg table, today, while it lasts.
One important caution: there may be two condo markets here, not one. Everythign about is islandwide. But an apartment-zoned condo facing the end of short-term rentals under Bill 9 and a hotel-zoned condo that isn't affected are very different purchases, and they may not be finding their floors at the same time or at the same price. If rental income is part of your plan, the zoning of the specific building matter more than any islandwide average, and that's conversation to have with us before you write an offer, not after. We're working on pulling these two segments apart in the data for a future report. And given how the rezoning process is going so far, don't assume Bill 88 will rescue an apartment-zoned building.
And the hedge, because you know it's coming. Pending sales dipped to 91 in September, so the next month or two of closings could cool. Condos that sold in September took an average of 210 days to get there, the longest in our data, and active listings keep aging. This is not a market where you have to rush. It is a market where the best units at the right prices are getting picked off by patient, prepared buyers, and the window to be one of them may not stay this wide.
For Condo Sellers: "We Don't Need to Sell"
Almost every week, someone tells us, "We'd like to sell, but we don't need to sell." Or, "We just want to test the market and see what happens." I understand the instinct completely. But I owe you a clear-eyed answer, and two years of data give it.
First, the market has moved a long way since you last checked. If your reference point for your condo's value is a sale, an appraisal or a neighbor's price from 2023 or 2024, the typical condo sale has come down about 29% since then by the median, and more by the average. Now, an important distinction: that's the market as a whole, not necessarily your unit. Medians and averages shift with the mix of what sells, and the only reliable way to know what your condo is worth today is to compare it with recent sales of similar units, ideally in your own complex. But most owners anchor to the best number they ever heard, and in this market taht anchor can since a listing.
Second, buyers are making offers well below asking. In the deals we're working right now, offers 20% below the asking price are not uncommon. The broader numbers point the same way: the median asking price on active listings is $747,000, while the median condo that actually sold in September went for $660,000. Those are different groups of condos, so it's not a precise discount, but that gap where today's negotiations live. Buyers know they have choices, and they're writing offers accordingly.
Third, "testing the market" mostly tests your patience. A listing that expires or gets withdrawn is a listing that didn't sell. Three years ago, in the twelve months ending September 2024, 98 condo listings expired and 429 were withdrawn, 527 in all, against 879 sales: about 6 listings failed to sell for every 10 that closed. This past year, 323 expired and 633 were withdrawn, 956 in all, against 798 sales: about 12 for every 10. More condo listings now end without a sale than with one. September alone: 79 listings came off the market unsold, against 72 sales. Active listings now average 183 days on market, up from 154 a year ago and 126 two years ago, and even the condos that sold in September had been on the market for an average of 210 days. A listing that sits builds a history every buyer's agent can see, and stale listings attract exactly the lowball offers a "just testing" seller won't accept.
So here's my advice. If you actually want or need to sell, price to where buyers are today, not to 2024, and you'll find there are buyers for the right condo at the right price. Sales are up 20% this year for a reason. If you don't want or need to sell, the best move may be not ot list at all. Keep enjoying your place, and if you want to know what it's worth, call us for a private valuation based on recnet sales in your own complex. It costs you nothing, it leaves no trail on the MLS, and it gives you a real number for when the time is right.
On the zoning question: Bill 88 is law, and the county's rezoning process is working its way through the council and the planning commissions. For hopeful condo owners, I'd say it is not going well. The vast majority of condos that have been passed from the county council to the planning commission have been rejected by the planning commission. Owners of apartment-zoned complexes that have been turned down by the planning commission can hope the council will save them with a supermajority vote, but that seems very unlikely, and I expect lawsuits may follow. And it's important to understand that even the complexes that haven't gotten a thumbs-down also have not been rezoned yet, and no owner's rental clock has changed. We'll have a full update in a separate post later this month, so stay tuned.
Bottom line on condos: over three years, condo prices came down about 30% and sales hit bottom and turned. Over the last year, the price decline has nearly flattened while closings and pendings climbed and supply tightened. Add rising mortgage rates, and for buyers that's a window worth taking seriously. For sellers who don't need to sell, it's a reason to stay put rather than test.
* Data collected on the 1st of the following month. September figures were collected October 1, 2026. Multi-year comparisons cover October 2023 through September 2026.
* Mortgage rates per Freddie Mac Primary Mortgage Market Survey, October 8, 2026. Payment examples show principal and interest only on a 30-year fixed loan with 20% down.
Key Takeaways: Condos
798 condo closings over the past twelve months, up about 20% from 667 the year before, after falling from 879 the year before that. Pending turned first, in late 2024.
The median condo sale is down about 29% from two years ago; the average, about 35%. The last two years had the same dollar volume, about $775 million with buyers getting 20% more condos for it.
The year-over-year median decline peaked at about 29% in the third quarter of 2025 and has narrowed to about 3%. Three of the last four quarterly medians sat between about $616,000 and $637,000.
About 11 months of supply at the recent pace, down from about 16 a year ago, though inventory remains far above 2023 and 2024 levels.
30-year mortgage rates hit 7.40%, up seven straight weeks. On a $660,000 condo with 20% down, that's about $390 a month more than a year ago, roughly equal to 10% price increase.
Apartment-zoned condos affected by Bill 9 and hotel-zoned condos may be different markets. Check the zoning before you rely on islandwide numbers.
For sellers: about 12 listings no expire or are withdrawn for every 10 that sell, up from about 6 three years ago. Active listings average 183 days, and offers 20% below asking are not uncommon.
_________________________
Single-Family Homes
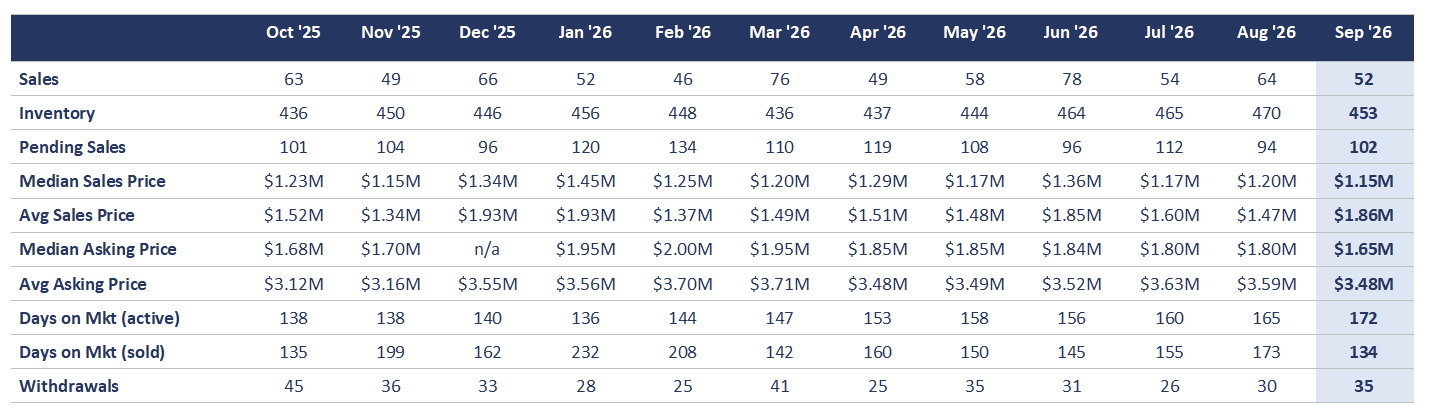
Last month we flagged that home pendings had fallen to 94 and warned that September closings could cool. They did. 52 homes closed in September, down from August's 64 and below the trailing twelve-month average of about 59. The median eased to $1,150,000, matching last November for the lowest reading in this table, while the average jumped to $1,861,394 on a handful of luxury closings. In this market, even a handful of luxury closings is noteworthy, so we'll detail that in our monthly luxury market report.
The longer view is where homes and condos part ways. Two years ago, while conod prices were already falling year over year, home prices were holding steady. Now it has flipped. Home closings over the past twelve months totaled 707, about 3% more than the year before and roughly level with the 718 of two years ago. But prices are giving ground. The sales-weighted average home price fell about 12% year over year, and the third-quarter median, about $1.17 million, was roughly 10% below the same quarter last year, the widest year-over-year gap of the past two years. Condos look like they're finding their floor. Homes are still looking for theirs.
Supply backs that up. Active home listings eased to 453 from August's high of 470, but that's still up from 438 a year ago, 335 two years ago and 212 three years ago. At the recent sales pace that's about 8 months of supply, up from about 7.5 a year ago. Active listings now average 172 days on market, a new high, and 16 listings expired in September, the most in this table. Pending sales recovered to 102 from 94, which suggests October won't fall off a cliff, but they've averaged about 6% fewer than the year before. And the rate story applies here as much as anywhere: on a financed purchase at these price points, a full point of rate is real money every month.
Bottom line on homes: a cooler September, as the pending count warned, on top of a longer-term picture of flat sales, rising supply and softening prices. A thin market leaning a little more toward buyers each quarter.
* Data collected on the 1st of the following month. September figures were collected October 1, 2026.
* December '25 median asking price unavailable.
Key Takeaways: Homes
52 homes closing in September, down from 64, at last month's low pending count warned.
Median sold prices eased to $1,150,000 matching the table low, while the average jumped to about $1.86M on luxury closings.
Over twelve months, home sales were essentially flat (up about 3%), while the average price fell about 12%. The third-quarter median was about 10% below a year ago.
Inventory at 453, up from 438 a year ago and 212 three years ago. About 8 months of supply.
Active listings average 172 days on market, a new high; 16 expirations, the most on the table.
_________________________
A Quick Word on Land
Eight vacant-land parcels closed in September against 232 active listings, the most on the market all year and up from 218 in August. The median sale price came in at $579,500. With eight sales, the median goes wherever those eight parcels happen to sit, so please don't draw a trend line through it. The trend that is real; land inventory has climbed four months running, and at 232 it's well above the 179 of a year ago. Land is a thin, patient market you measure in seasons, not months, and right now the season favors the buyer with vision and a long fuse.
Our Take
This month the most important numbers in the report aren't from September. They're from the three years behind it.
Condo buyers have spent two years being told to wait, and the waiting paid off. The median condo sale came down about 29%. The question now is whether waiting still pays, and the evidence says we've probably reached the point of diminishing returns. The year-over-year price decline has shrunk from about 29% to about 3%. Sales are up about 20%. Supply has dropped from about 16 months to about 11. And the 30-year mortgage rate has climbed seven straight weeks to 7.40%, quietly erasing the equivalent of a 10% price cut for anyone who finances. We're not calling a bottom. We're telling you that lower prices, real negotiating leverage and rising rates rarely line up this neatly, and the buyers who move while they do tend to look smart later. Just know which kind of condo you're buying, because apartment-zoned and hotel-zoned may be two different stories.
Condo sellers, the same facts point the other way. The market has moved a long way since 2023 and 2024, buyers know it, and they're writing offers accordingly, sometimes 20% below asking. And sometimes that works for them. Count expired and withdrawn listings together and about 12 condo listings now fail to sell for every 10 that do, double the rate of three years ago. If you want or need to sell, price to the market that exists today and you'll find a buyer. If you don't, testing the market is mostly a way to spend six months collecting offers you won't accept and getting frustrated with your broker. Call us for a private valuation instead.
Which brings me to the thing I say every month, because it refuses to stop being true. There is no single “Maui real estate market.” You can stand in the Kihei sun and watch rain fall Upcountry at the same time; same island, two completely different afternoons. Condos look like they're finding their floor while homes are still softening. Apartment-zoned and hotel-zoned condos may be on different clocks. And the well-priced listing and the one still asking for 2024 are living in different markets entirely. Our job is to help you read the slice that actually touches you.
The same thing we say every month still holds: the most expensive thing you can do in a market like this is wait without information.
Let's Talk Story
If you have questions about your property's value, what those numbers mean for your situation, or whether this market is your moment to make a move, reach out anytime. We're here as a resource for the Maui community, whether you're ready to act or just trying to make sense of the headlines. No pressure, no agenda, just a conversation.
And if you or someone you know is thinking about buying, selling, or simply keeping track of Maui's real estate market, we've got a fabulous team of seasoned, well-trained advisors standing by to help.
You can search every property listed for sale at www.AlohaGroupMaui.com, or email me directly at lee@alohapotts.com. I answer every one.
From the greatest island on Earth, I'm Lahaina Lee, saying ALOHA.