By Lahaina Lee, Aloha Group Maui | October 2026 market data
Prefer to listen? This report is also an episode of the Maui Real Estate Advisor podcast.
My business partner Barbara Potts, aka The Boss, took one look at the October numbers and said the market looks like it's sleepwalking. Then she asked the question I haven't been able to shake since: what are buyers waiting for? It's a fair question. Homes and condos combined finished October with just 174 pending sales, the lowest October count in our records going back to 2012, and second only to last December's 171 for the lowest month of any kind. At the same time, 1,262 homes and condos sat on the market. That's a lot of choice and not much commitment. The elections are now behind us. The Federal Reserve held rates steady on October 28. Mortgage rates have eased three weeks in a row. And the typical condo sale is back to roughly where it was in 2021. So this month we take Barbara's question seriously, walk through the usual suspects one at a time, and look at what the data says about each. Fair warning: this month's big averages have a story behind them too. Here is what the data shows, what it means, and where we hedge.
November 2026 Key Takeaways
- The pipeline: 174 pending home and condo sales combined, the lowest October in our records back to 2012. October pendings have now fallen three years running: 207, 192, 174.
- The supply: 1,262 homes and condos for sale. Buyers have plenty of choice. They just aren't committing.
- Condo averages: The average condo sale jumped to $1,223,993 on six new-development closings at Makena Beach Club. Without them, the other 62 closings averaged $779,079. The $634,500 median tells the truer story.
- Home averages: The average home sale held above $1.8 million, at $1,876,271, helped by five closings on homes listed above $4 million, including $18.5 million and $8.5 million sales in Makena. The median was $1,179,000.
- Condo days on market: Sold condos averaged 216 days on market in October, but six Makena Beach Club units listed for 703 to 885 days account for much of that. By our math, the other 62 averaged roughly 150 to 170 days. Active listings average 175 days.
- Condo prices vs. 2021 and 2022: The median condo sale averaged about $650,000 over the past twelve months, about 16% below the twelve months ending October 2022 and about 29% below the 2024 peak. Essentially back to 2021 (when COVID was still impacting travel on Maui).
- Home prices: A different story. About 5% below last year's peak, but still about 11% above 2022 and about 28% above 2021.
- Rates: The 30-year fixed eased to 7.18% on November 5, down three straight weeks from 7.40% in early October, but still nearly a full point above the 6.22% of a year ago. The Fed held steady, and the two dissenters wanted a hike, not a cut.
First, a Word on This Month's Averages
Every so often a handful of sales moves the averages so far that they stop describing the typical sale. October was one of those months, on both sides of the market.
On the condo side, six of October's 68 closings were at Makena Beach Club, all new-development sales handled in-house by the developer to buyers who were not represented by their own agent. Those six pushed the average condo sale over the $1 million mark, to $1,223,993. Take them out and the other 62 closings in the Maui MLS averaged $779,079, which would have been the second-lowest monthly average in our twelve-month table. The median, which a few big sales barely move, came in at $634,500, a little below September's $660,000 and a little above the $614,000 of a year ago.
On the home side, the average held above $1.8 million, at $1,876,271, helped along by five closings on homes listed above $4 million, including sales of $18.5 million and $8.5 million in Makena. By our math, take out just those two Makena sales and the average for the other 57 homes drops to about $1.47 million. The median, $1,179,000, again tells the steadier story.
None of that makes those sales less real. Luxury buyers on Maui do a lot of things, except hurry, and when they do close, they close big. It just means that this month, the median is the number to watch.
One more thought on those Makena Beach Club sales, for anyone shopping new development. A developer's in-house sales team works for the developer. That's not a criticism; it's how new development works. But whether you're buying a resale condo or a brand-new unit, it pays to have someone at the table whose only job is to represent you.
What Are Buyers Waiting For?
Barbara's question deserves a real answer, so let's start with the long view. Here are five back-to-back twelve-month periods, each ending in October.
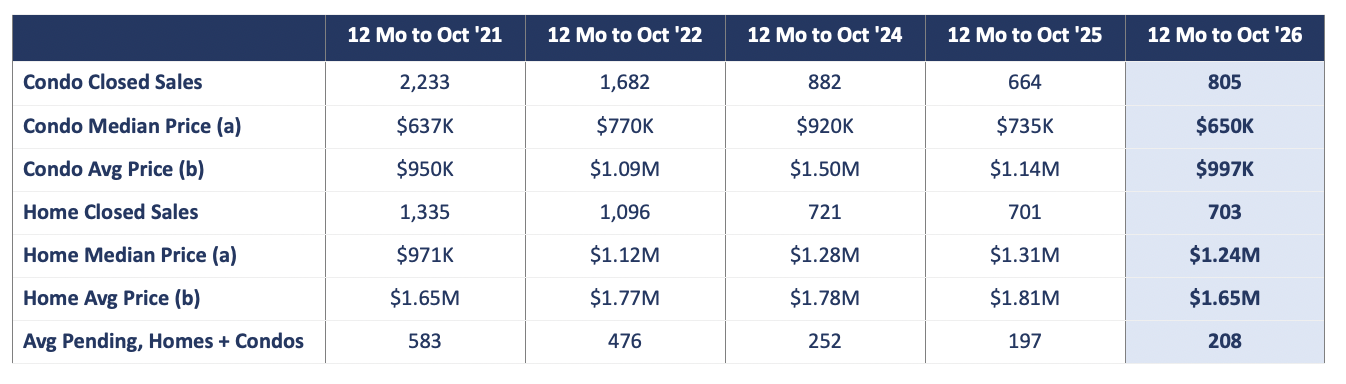 (a) Average of the monthly medians in each period. (b) Weighted by the number of sales in each month.
Now the usual suspects, one at a time.
Waiting for the elections? They're over. Whatever you think of the results, the uncertainty of not knowing is gone. If the election was the reason to wait, that reason expired on November 3.
Waiting for lower interest rates? This is the big one, and the news is mixed. On the plus side, Freddie Mac's 30-year fixed average eased to 7.18% on November 5, the third straight weekly decline, down from 7.40% in early October. But that's still nearly a full point above the 6.22% of a year ago. And on October 28 the Federal Reserve held its benchmark rate steady at 3.75% to 4.00%, with two members dissenting in favor of a rate increase, not a cut. I can't tell you where rates go next; nobody reliably can. But if you're waiting for the Fed to ride to the rescue, the Fed itself isn't signaling that it's on the way.
Here's what the past year of rate moves has already cost. Take a condo at October's median of $634,500 with 20% down. At 6.22%, principal and interest run about $3,115 a month. At 7.18%, about $3,439. That's about $323 more every month, close to $3,900 a year, roughly the same as paying 9% more for the condo. The 1% equals 10% rule at work again: for every point rates rise, buyers lose about 10% in purchasing power. Cash buyers, and many of our mainland second-home buyers are exactly that, don't feel the payment, but they do benefit from every financed buyer the rates sideline.
Waiting for lower prices? For condos, they already came. Over the past twelve months the median condo sale averaged about $650,000. That's about 16% below the twelve months ending October 2022, about 29% below the peak in the twelve months ending October 2024, and essentially back to the roughly $637,000 of the twelve months ending October 2021. The median asking price on active condo listings is down to $749,000, from $799,000 a year ago.
Homes are a different story, and this is where I'd push back on the idea that everything on Maui got cheaper. The median home sale over the past twelve months averaged about $1.24 million. That's about 5% below the peak of a year ago, but still about 11% above the twelve months ending October 2022 and about 28% above 2021. Home buyers waiting for 2021 prices may be waiting a long time.
Waiting for zoning clarity? For apartment-zoned condos, this one is legitimate. On September 29 the county council sent 32 shoreline complexes to the planning commission to be considered for hotel zoning under Bill 88. In late October, on a 5 to 4 vote, the council declined to send four more: Nohonani and Hoyochi Nikko in Lahaina, and Maalaea Kai and Island Sands in Maalaea. Under Bill 9, vacation rentals in apartment districts end December 31, 2028 in West Maui and December 31, 2030 elsewhere. If rental income is part of your plan, waiting for clarity on a specific building is reasonable. It isn't a reason to sit out the whole market, and hotel-zoned condos aren't affected.
So is the market really asleep? Partly. The sales pipeline is thin right now: October pendings have fallen three years running, 207, 192 and now 174. Some of that is the calendar, too; pendings usually soften heading into the holidays, which is why last December's 171 is the only lower month in our records. But look at the twelve-month numbers in the table. Condo closings are up about 21% from a year ago, and pending sales over the past twelve months averaged a little higher than the year before. It's not that nobody is buying. It's that the buyers who are active are slow, selective and in no rush, and the condos that sell are the ones that have sat long enough for their sellers to meet the market. That's a buyer's market doing exactly what buyer's markets do.
So what are they waiting for? My read is that most of them are waiting for certainty, and certainty is the one thing this market, or any market in the last few years, isn't willing to give us.
Condos
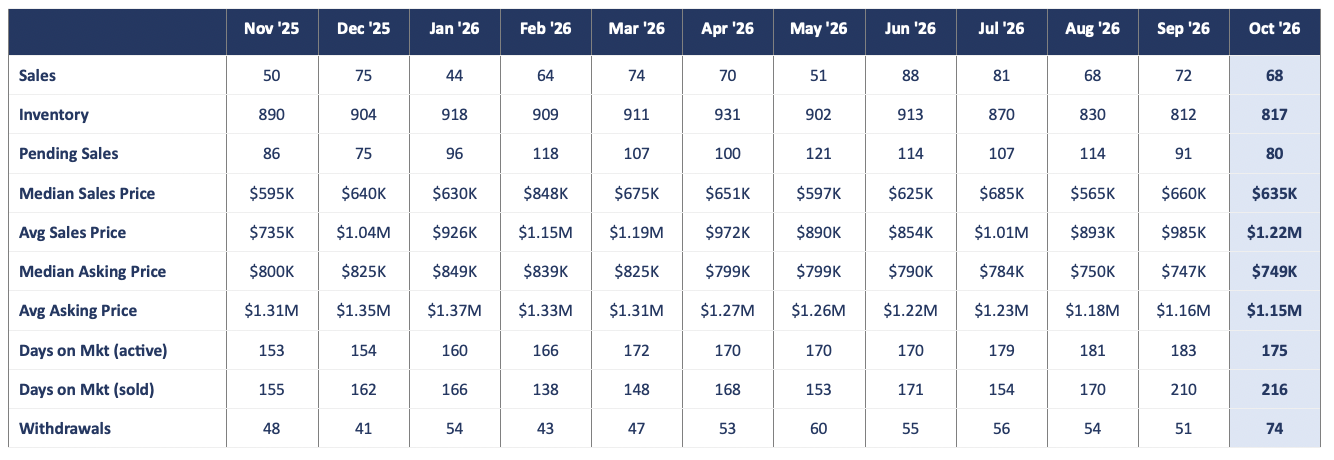
October's condo closings came in at 68, down a touch from September's 72 but up from 61 a year ago. Over the past twelve months, 805 condos closed, about 21% more than the 664 of the year before. Active inventory held at 817, essentially flat with September's 812 and 114 below April's peak of 931. At the recent three-month sales pace, that works out to just under 12 months of supply, down from about 15 a year ago. Still a buyer's market, but a less lopsided one.
The number that worries me is pending sales. Condo pendings fell for a second straight month, to 80, down from 114 in August and the lowest count since last December. Last month we warned that falling pendings could cool October closings. Closings held up reasonably well, but the pipeline for November and December is thinner still.
Then there's days on market. On paper, condos that sold in October had been on the market an average of 216 days before closing, up from 210 in September and 180 a year ago. But here the Makena Beach Club sales matter again. Those six new-development units had been listed in the MLS for between 703 and 885 days, and long listing periods are common with new development, which is often listed well ahead of completion. By our math, the other 62 condos averaged somewhere around 150 to 170 days, right in line with the past year. So October's headline number isn't a new sign of buyers stalling.
What is real: condos are still taking a long time to sell. September's 210 days was the longest since August 2024, and active listings now average 175 days on market, down slightly from September's 183 but up from 154 a year ago. The condos that are selling are mostly the ones that have been sitting, often after a price cut or two, and patient buyers are picking them off.
For condo sellers, October was a rough month. 74 condo listings were withdrawn, the most in our twelve-month table, and another 34 expired. That's 108 listings that came off the market without selling, against 68 that sold: about 16 failed listings for every 10 sales. Over the past twelve months it's about 12 for every 10. If you want or need to sell, price to where buyers are today and you'll find one. If you don't, call us for a private valuation instead of testing the market. It costs nothing and leaves no trail on the MLS.
Bottom line on condos: prices are back to 2021 levels, sales over the year are up, supply is tightening slowly, and the buyers who are out there are taking their time and taking the listings that have already come to them. Is this the bottom of the market? The next few months will tell the tale as we work through our shoulder season and start into our traditional winter busy season.
* Data collected on the 1st of the following month. October figures were collected November 1, 2026. Twelve-month comparisons cover November 2020 through October 2026.
* Makena Beach Club figures, the $779,079 average excluding them, and their 703 to 885 days on market are based on our review of October closings in the Maui MLS. The 150 to 170 day range for the other 62 closings is estimated from that range.
* Mortgage rates per Freddie Mac Primary Mortgage Market Survey, November 5, 2026. Payment examples show principal and interest only on a 30-year fixed loan with 20% down.
Key Takeaways: Condos
- 68 closings in October, up from 61 a year ago. 805 over the past twelve months, up about 21%.
- The average sale jumped to $1,223,993 on six Makena Beach Club closings; the other 62 averaged $779,079. Median: $634,500.
- Pending sales fell to 80, the lowest since last December, so the next couple of months could be quiet.
- Sold condos averaged 216 days on market; without the six Makena Beach Club units (703 to 885 days each), roughly 150 to 170. Active listings average 175 days.
- Twelve-month median about $650,000: about 16% below 2022, about 29% below the 2024 peak, essentially back to 2021.
- 108 listings withdrawn or expired against 68 sales in October. Just under 12 months of supply.
Single-Family Homes
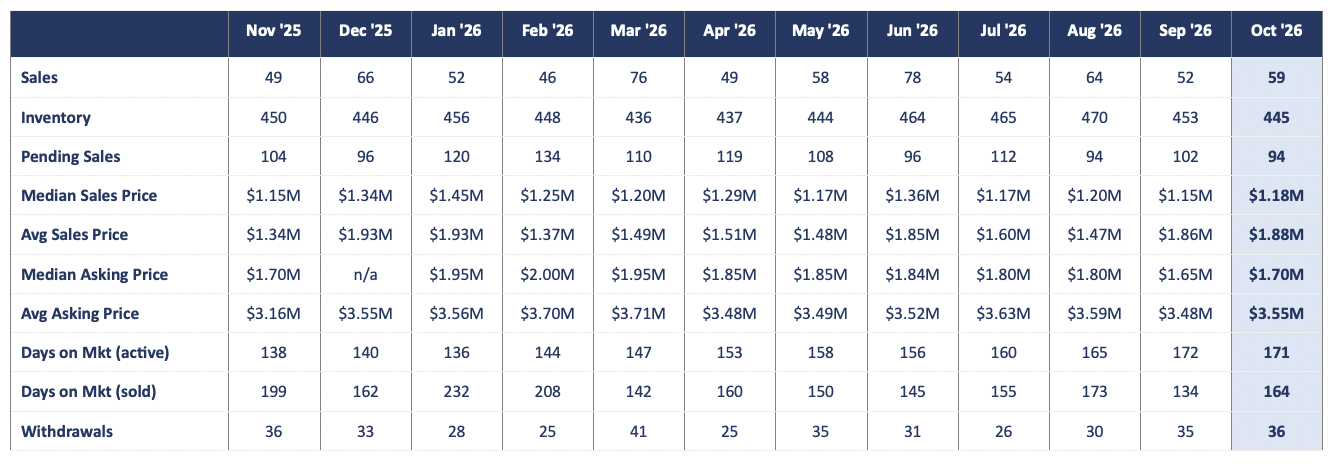
59 homes closed in October, up from September's 52 but below the 63 of a year ago. Over the past twelve months, 703 homes closed, essentially identical to the 701 of the year before. The median slipped to $1,179,000, about 4% below the $1,234,000 of a year ago, while the average held at $1,876,271 on the luxury closings described above.
Inventory eased to 445 from September's 453, still up from 436 a year ago. At the recent three-month sales pace, that's about 7.6 months of supply, a bit more than the roughly 7.3 of a year ago. Active listings average 171 days on market, just off September's 172 and among the highest readings in our data. Homes that sold took an average of 164 days, up from 134. 36 listings were withdrawn and 14 expired.
The caution flag is pendings. Home pendings fell back to 94, matching August for the second-lowest count in our records; the lowest, 92, came in January 2025. Last month a low pending count correctly warned of a cooler September. If the pattern holds, November home closings could be soft.
Bottom line on homes: flat sales, slowly rising supply, and prices about 5% off their peak but nowhere near 2021 levels, with a thin pipeline heading into the holidays.
* Data collected on the 1st of the following month. October figures were collected November 1, 2026.
* December '25 median asking price unavailable.
Key Takeaways: Homes
- 59 home closings in October, up from 52 in September, down from 63 a year ago. Twelve-month sales flat at 703.
- Median $1,179,000. Average $1,876,271, lifted by five closings on homes listed above $4 million; without the $18.5 million and $8.5 million Makena sales, about $1.47 million.
- Twelve-month median about $1.24 million: about 5% below last year's peak, still about 11% above 2022 and 28% above 2021.
- Inventory at 445, about 7.6 months of supply. Active listings average 171 days.
- Pending sales at 94, tied for the second-lowest in our records.
A Quick Word on Land
Eleven vacant-land parcels closed in October against 232 active listings, unchanged from September and well above the 199 of a year ago. The median sale price came in at $625,000. Parcels that sold took an average of 606 days to get there, among the longest in our data, but with eleven sales that says more about a few long-listed parcels than about the market. Pendings dipped to 14, and 14 listings were withdrawn. Land remains a thin, patient market you measure in seasons, not months.
Our Take
Barbara's right: on the surface, this market looks like it's sleepwalking. Pendings are the lowest of any October in our records, active condo listings have been sitting nearly six months on average, and sellers pulled more condo listings in October than in any month this year.
But let's be clear about what buyers are actually waiting for, because most of the reasons have already run out. The elections are over. Condo prices are back to 2021 levels. Asking prices have come down, and sellers are accepting offers they wouldn't have looked at twice a year ago. The one thing that hasn't come back is cheap money, and the Fed's own vote suggests it isn't coming back soon. Waiting for lower prices and lower rates at the same time is a bet on two things going your way at once.
There are good reasons to wait on specific things. If you're eyeing an apartment-zoned condo for rental income, the zoning process deserves your full attention, building by building. If you're shopping for a home and holding out for 2021 prices, the data says those aren't coming back any time soon. But for condo buyers with a long horizon, today's mix of choice, leverage and prices is the kind that will have future shoppers saying, “I should have bought in 2026.”
And for sellers: when buyers are this selective, the listing priced for last year is the one that sits for six months or more, or gets withdrawn. Price to today's market, or why bother? The next few months look like a great time to sell, at market price.
Which brings me to the thing I say every month, because it refuses to stop being true. There is no single "Maui real estate market." You can stand in the Kihei sun and watch rain fall Upcountry at the same time; same island, two completely different afternoons. Condo prices are back to 2021 while home prices are not. A new-development buyer in Makena and a resale buyer in Kihei are living in different markets entirely. Our job is to help you read the slice that actually touches you.
The same thing we say every month still holds: the most expensive thing you can do in a market like this is wait without information.
Let's Talk Story
If you have questions about your property's value, what these numbers mean for your situation, or whether this market is your moment to make a move, reach out anytime. We're here as a resource for the Maui community, whether you're ready to act or just trying to make sense of the headlines. No pressure, no agenda, just a conversation.
And if you or someone you know is thinking about buying, selling, or simply keeping track of Maui's real estate market, we've got a fabulous team of seasoned, well-trained advisors standing by to help.
You can search every property listed for sale at www.AlohaGroupMaui.com, or email me directly at lee@alohapotts.com. I answer every one.
From the greatest island on Earth, I'm Lahaina Lee, saying ALOHA.